


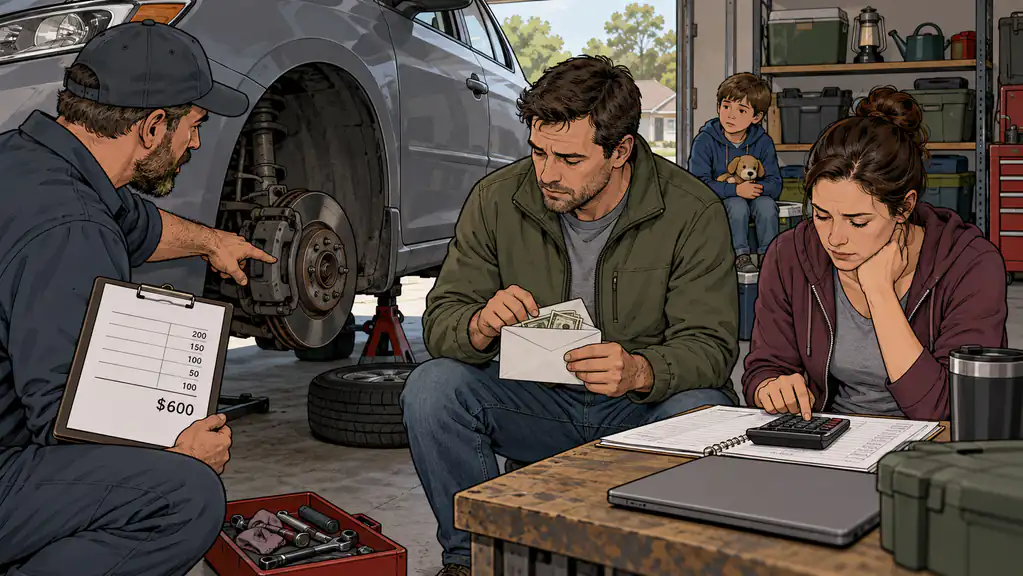
If you already prep, you’ve probably got food, water, and gear handled better than most people you know. But run the threat math honestly and something plain and unglamorous climbs above the pandemic and the grid-down: the surprise expense. High odds, real bite, and — unlike almost everything else you prep for — it’s coming more than once. A prepper with a year of food who can’t cover a $700 car repair doesn’t have a fortress. He’s got a wall with a hole in it.
Economic hardship at the household level isn’t the financial system falling over. It’s the ordinary, repeating shock — cut hours, a medical bill, a dead appliance, an insurance deductible — that rattles a household but rarely wrecks a ready one. That word “rarely” is the whole game. With a buffer behind it, it’s a setback you shrug off. Without one, it’s the first domino.
Why the boring threat beats the dramatic ones
Preppers love the tail risks — the rare, huge events. But the math that ranks threats multiplies how likely by how bad, and the surprise expense scores high on likely precisely because it’s not rare. It happens to nearly everyone, over and over. Any single hit is minor, which is why the bite lands mid-scale — but you’re not facing one hit over a lifetime. You’re facing a stream of them.
That changes where your effort goes. The dramatic threats earn some prep. This one earns prep first, because it’s the one that’s highly likely to test you, and the one where a small, cheap move cuts the most real risk. That’s not budgeting; that’s preparedness aimed at one of the likeliest threats to come.
The cascade is the whole mechanism
A small event turns into a big crisis through second and third effects. Trace one $600 shock through a household with nothing set aside:
- It goes on a credit card at 20 to 25% interest.
- The balance bumps the minimum payment, which now competes with next month’s groceries.
- A tight month means a late payment somewhere — a fee, and a rate bump on top.
- The next surprise, and there’s always a next surprise, lands on a budget that’s already stretched with no slack left.
Every step is small. The compounding is what breaks you. A buffer stops the whole thing at step one. That’s why the fix isn’t “earn more” — slow, and not fully in your hands — it’s “hold a reserve,” which is immediate and entirely yours.
Plan for “again,” not “if”
Be honest about the odds, because honesty is the point. For a rare regional hazard, “it probably won’t hit you this decade” is a fair read. This is the opposite. Over any few-year window, the chance that some version of this reaches your household runs high. Tires wear out. Bodies get sick. Employers reshuffle. Roofs leak.
And most households sit closer to the edge than they’d like. The Federal Reserve’s 2023 survey found only 63% of US adults could cover a surprise $400 expense with cash or its equivalent, and 13% couldn’t cover it by any means — which is exactly how a small event turns into a spiral. So the planning question isn’t whether. It’s how often, how big, and whether your reserve refills between hits. You’re not building a fund for one event. You’re building a shock absorber that has to keep working across many.
Setback or crisis is a choice you make early
The rating puts the bite mid-scale, and that’s right — but only conditionally. The same exact event sits at two very different places depending on one thing: do you have a reserve?
- Reserve there: the bite is small. You pay it, top the fund back up over a few months, done.
- Reserve gone: the bite climbs, because you’ve just added debt, fees, and stress that outlast the original event by months.
You don’t get to pick which surprises come. You do get to pre-decide which side of that line you’re standing on. And you make that decision in the calm months — not the crisis one.
Measure it in time, and do the math
Treat money like any other supply: measured in time, not dollars. Three numbers turn a vague worry into a plan.
- Burn rate — your real monthly floor. Housing, utilities, food, insurance, minimum debt, gas. Not your comfortable spending — your stripped-down survival number.
- Buffer — cash you can reach in a day, held separately so it doesn’t quietly get spent.
- Runway = buffer ÷ burn rate. That’s your readiness, in months.
Put numbers on it. Say your bare floor is $2,500 a month. A $500 starter fund is six days of runway — enough to eat most single surprises, not much more. Get it to $2,500 and you’ve got one month. Get it to $7,500 and you’ve got three months — and now a lost job is a problem you manage, not a panic. Same household, same paycheck; the only thing that changed is what you set aside when things were fine.
The four moves
- Build a separate “oh no” fund. The separation is the point — money sitting in checking gets spent by ordinary life. Even $500 to $1,000 covers most common surprises. This is the highest-leverage prep there is, full stop. Nothing else you buy protects one of the things most likely to actually happen.
- Track your spending so you can cut fast. You can’t drop your burn rate in a pinch if you don’t know what’s in it. Know which costs are fixed and hard to cut, and which are discretionary and gone in a day. This isn’t budgeting for its own sake — it’s the ability to slam the burn rate down when income wobbles, which stretches every dollar of runway you’ve got.
- Keep high-interest debt low. Debt is a buffer with a minus sign — it multiplies setbacks instead of soaking them up. Kill the highest-rate balances first. Each one you clear frees up monthly cash and removes a compounding risk. That’s not a payment you dropped; that’s runway you bought.
- Keep a deep pantry. Food is your most flexible expense. A stocked pantry lets you flex grocery spending toward zero in a tight month and eat what you already bought when times were good (or prices were cheaper). This is the point where classic prepping and money prepping turn into the exact same move.
Bottom Line
- Run the threat math honestly and the surprise expense outranks the dramatic scenarios — high odds, recurring, and cheap to prepare for.
- The event rarely causes the crisis; having no buffer does. Stop it at step one.
- Plan for “again,” not “if.” Your reserve has to survive repeated hits, not just one.
- Readiness is runway = buffer ÷ burn rate, measured in months. That one number is your status.
- A separate fund, low high-interest debt, and a deep pantry are three shock absorbers — build them in the calm, not the crisis.
A cash buffer buys you time for one of the likeliest emergencies you’ll ever face. That’s not budgeting — that’s preparedness.
A deep pantry doubles as a financial buffer. Size yours with the Food & Water Storage worksheet, and check where this threat ranks for your household with Threat Planning.